Set Up a Limited Company UK: A Step by Step Guide
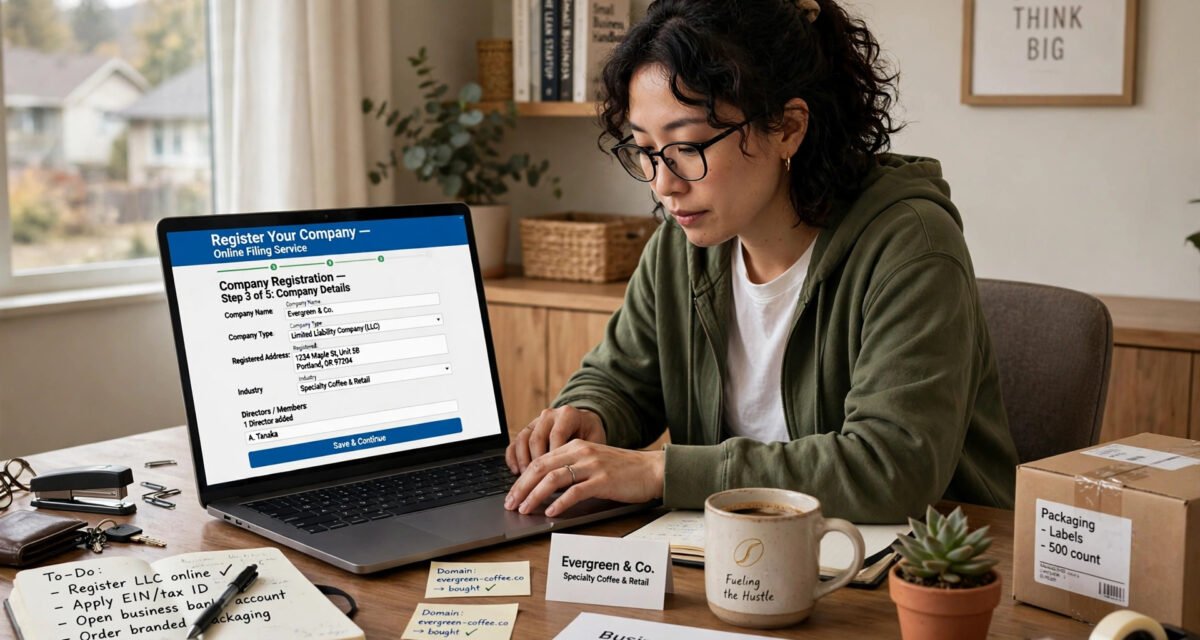
Starting a business is exciting, and for many founders the first big decision is how to structure it. Plenty of people begin as sole traders, then later set up a limited company as the business grows. Others form a company from day one. If you are weighing it up, it helps to understand the steps involved, because forming the company is the easy part. Running it properly is the ongoing commitment.
This guide walks through the main steps to set up a limited company uk founders go through, in order: choosing a name, deciding who directs and owns the company, preparing the registered address and business activity code, registering with Companies House, and dealing with tax registration. It also covers the duties that follow once the company exists.
Quick Takeaways
- A limited company is a separate legal identity from its owners, which is the main difference from being a sole trader.
- You need a company name, at least one director, at least one shareholder, a registered office address and an activity code.
- Registration is handled by Companies House, and the company normally registers for corporation tax with HMRC around the same time.
- A registration fee applies, so check the current amount on GOV.UK before you apply.
- Directors have legal duties, including keeping records, filing accounts and sending in a regular confirmation statement.
- Before you decide, weigh the extra admin against the benefits, and consider taking advice from an accountant.
Before You Start: Is a Limited Company Right for You?
A limited company is its own legal person, separate from you. It can own things, sign contracts and owe money in its own name. Because of that separation, your personal responsibility for company debts is normally limited to what you put in, which is where the word limited comes from. As a sole trader, by contrast, you and the business are legally the same, so business debts are your debts.
The trade off is admin. A company has public records, filing duties and stricter rules about how money moves in and out. Directors cannot simply treat the company bank account as their own pocket. Many founders also find that customers and lenders view a registered company as a more established outfit, which can help. Neither route is right for everyone, and the decision often depends on your income, your risk, and how you plan to grow.
Step 1: Choose a Company Name
Your company name must be available and must follow the naming rules. It cannot be the same as, or too similar to, a name already on the register, and it cannot be offensive or suggest a connection to government or other bodies that you do not have. Certain sensitive words need approval before they can be used.
Most private limited companies end their name with Limited or Ltd, although there are exceptions. Before you settle on a name, check it on the Companies House register, and also check whether the matching domain name and social handles are free if those matter to you. Remember that registering a company name does not give you trade mark rights, which are a separate process.
Step 2: Decide Directors and Shareholders
A private limited company needs at least one director and at least one shareholder. Very often, especially in small businesses, one person fills both roles. Directors run the company day to day and carry legal duties for how it is managed. Shareholders own the company through its shares and have the final say on major decisions.
When you register, you will state how many shares the company has and who holds them, because shares decide how ownership, voting power and any dividends are split. You will also give details of people with significant control over the company, which usually means the people who own most of the shares or voting rights. Think these choices through carefully if you are starting with a partner, because changing the split later can be awkward.
Step 3: Prepare the Registered Office Address and SIC Code
Every company needs a registered office address. This is the official address shown on the public record, and it is where Companies House and HMRC will send important post. It must be a real address where documents can be delivered and acknowledged. Some founders use their accountant’s address, with permission, rather than publish their home address.
You will also choose a SIC code, which is a standard code describing what the business does. You pick the code, or codes, that best match your main activity from the official list. It does not lock you into one trade forever, and it can be updated later, but it should give a fair picture of the business when you register.
Step 4: Register the Company with Companies House
Registration is done with Companies House, most commonly online, although a paper route also exists. As part of the application you provide the details from the earlier steps: name, address, directors, shareholders, shares and activity code. You also adopt the company’s constitution, which consists of the memorandum and articles of association. Many small companies use the standard model articles, while others take advice and tailor them.
A fee applies for registration, and the amount depends on how you apply, so check the current figure on GOV.UK before you start. Once the application is accepted, Companies House issues a certificate of incorporation, which confirms the company exists and shows its company number and date of formation. Keep that certificate safe. Banks and other organisations may ask to see it.
Step 5: Register for Corporation Tax
A limited company pays corporation tax on its profits, and it must be registered with HMRC for that purpose. In many cases the tax registration begins as part of setting up the company, and HMRC sends the company’s Unique Taxpayer Reference to the registered office by post. Guard that reference carefully, because you will need it to file company tax returns.
Depending on the business, other registrations may be needed too, such as VAT if turnover passes the threshold set by law, or PAYE if the company will employ staff, including paying you a salary as a director. These have their own rules, so review them early rather than after your first invoices go out.
After Registration: Your Ongoing Duties
Forming the company is the start, not the finish. Directors must keep proper company records, including accounting records that show money in and money out. Each year the company must prepare accounts and file them with Companies House, file a company tax return with HMRC, and pay any corporation tax due by the dates that apply. It must also send a confirmation statement at regular intervals to confirm that the information on the public record is up to date.
Changes must be reported too, such as a new director, a change of registered office, or changes to shares. Many founders open a business bank account in the company name to keep company money clearly separate from personal money, which makes record keeping far easier. Missing filings can lead to penalties and, in serious cases, the company being struck off, so a simple calendar of the key dates is one of the best tools a new director can set up.

Frequently Asked Questions
How long does it take to set up a limited company?
Online applications are often processed quickly, but the time can vary depending on checks and how busy the service is, and paper applications take longer. Plan around the whole process rather than the form alone: choosing the name, agreeing the shares and gathering the details is usually the part that takes founders the most time.
Can one person set up a limited company?
Yes. A single person can be the only director and the only shareholder, which is a very common arrangement for small businesses and freelancers. The company is still a separate legal identity, and the same filing duties apply, even when there is only one person involved.
Do I need an accountant to set up a limited company?
There is no rule that says you must use one. Many people register the company themselves and handle simple bookkeeping with software. Others prefer an accountant from the start, especially where shares, salaries and dividends need planning. The decision depends on your confidence with numbers and how complicated your affairs are.
What is the difference between a limited company and a sole trader?
A sole trader is the business: one person, personally responsible for its debts, with simpler admin and tax through self assessment. A limited company is separate from its owners, which limits personal responsibility for company debts, but it brings public records, filing duties and its own tax return. Each structure suits different situations.
Can I change my company name later?
Yes, a company can change its name through Companies House, following the proper process and checking the new name is available and allowed. You would then need to update your bank, invoices, website and contracts, so it is worth choosing carefully at the start to avoid the extra work.
A Note Before You Decide
This guide is general information only. It is not professional, legal or tax advice, and it does not cover every rule that might apply to your situation. Rules and fees change over time, so check the current position on GOV.UK and with Companies House before you act. If the decision matters to your income or your plans, consider speaking to an accountant first.
Conclusion
To set up a limited company uk founders follow a clear order: choose an available name, decide the directors and shareholders, prepare the registered office address and activity code, register with Companies House, and register for corporation tax. None of the steps is difficult on its own. The discipline lies in doing them in the right order and keeping up with the duties that follow.
If the structure fits your plans, form the company properly, set up a simple system for records and dates from day one, and the admin will stay manageable. Then you can get on with the real job: building the business the company was created for.
Over to You
If you have formed a company, which step took you longest: the name, the shares, or the paperwork afterwards? Share your experience in the comments. New founders reading this guide will thank you for the warning, or the shortcut.

magazinesupdate
Sharing practical guides, news and insights on Magazines Update.